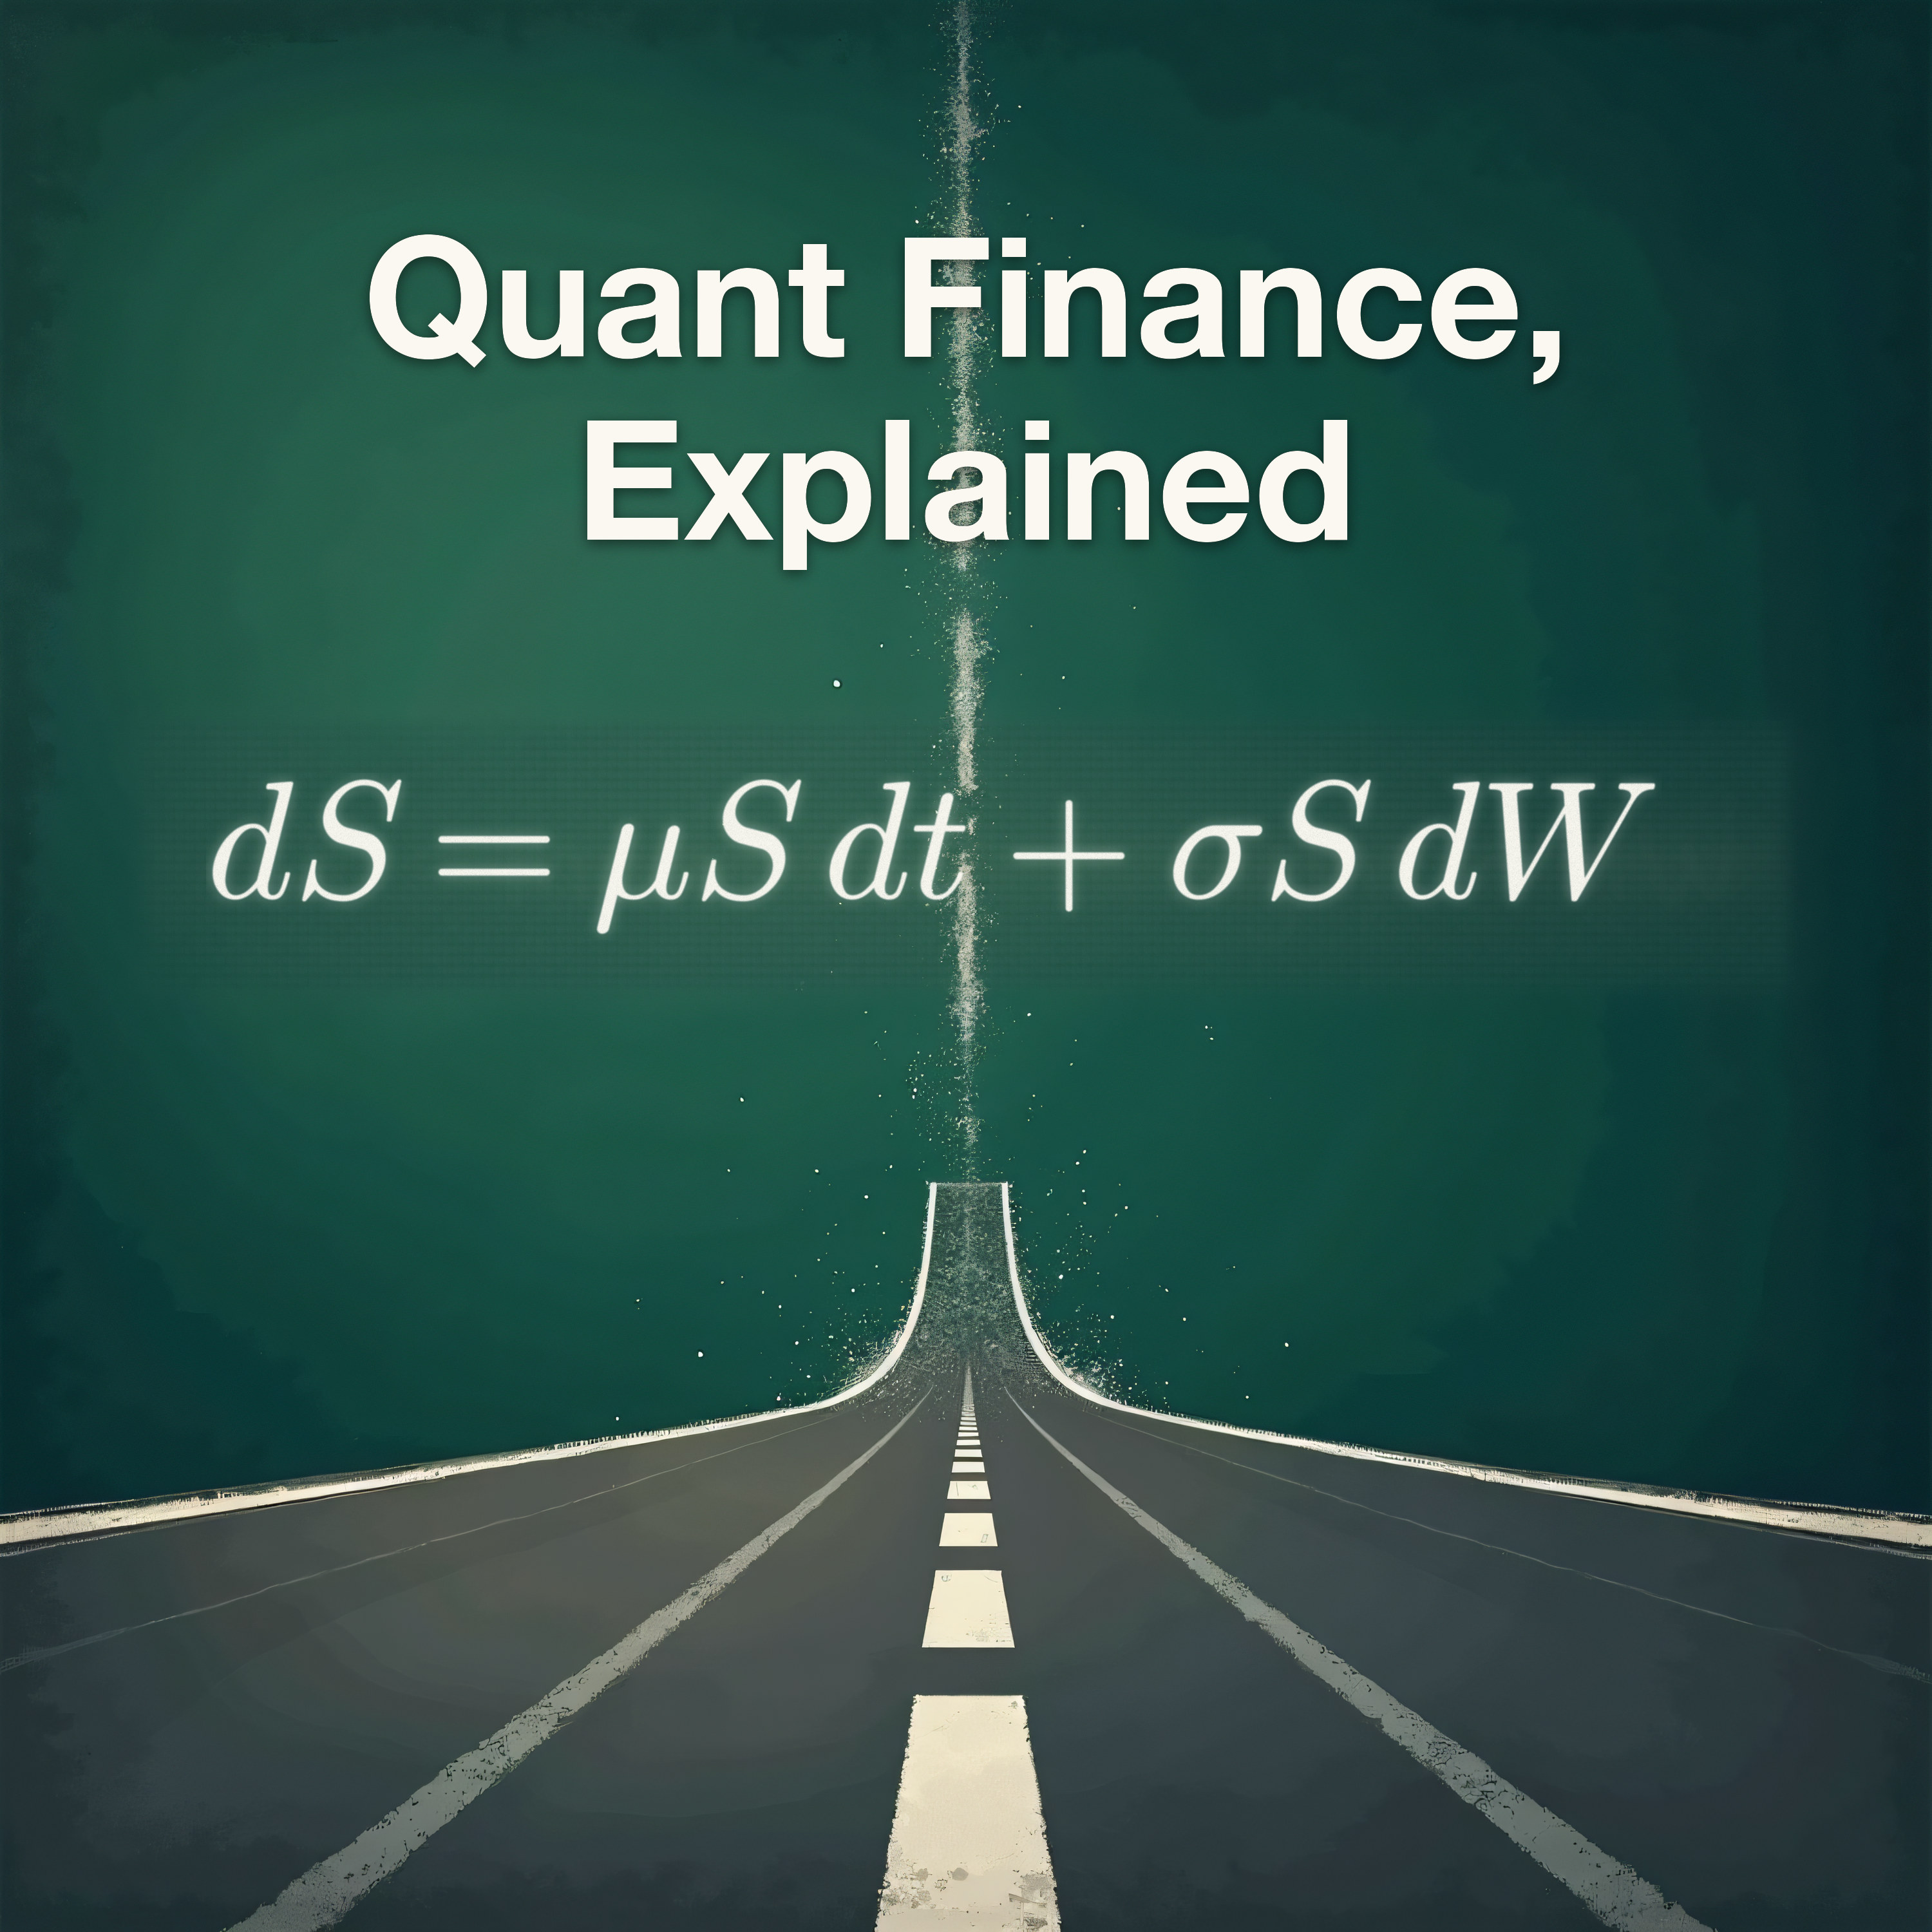
Learn quantitative finance top-down: the dynamics and vocabulary behind prices, options, hedging, volatility, and stochastic calculus, one idea per episode, built for drive time, with an AI model as your patient expert. Episodes follow a quant finance textbook's order. For educational purposes only; not financial advice.
Site
RSS
Apple
Data updated on 23/10/2026
Recent rankings
Latest chart positions across Apple Podcasts and Spotify rankings.
Shared links between episodes and podcasts
Links found in episode descriptions and other podcasts that share them.
Discover shows related to Quant Finance, Explained, based on actual content similarities. Explore podcasts with similar topics, themes, and formats, backed by real data.
There is no related content for this show.
No links shared by this podcast
The Greeks: How an Option Price Moves
Season 1 · Episode 9
Friday, October 9, 2026 • Duration 20:57
Course episode nine, Wilmott chapter eight. A price is useful for
about one second; then the stock moves, a day passes, volatility
shifts. The Greeks are the sensitivities that say how the price
responds. The episode opens with the vocabulary of the value sheet:
boundary conditions (state the edges first), marching backward from
expiry, the diffusion picture in which a sharp payoff corner becomes
a smooth curve, partial derivatives (a rate of change in one
direction with the others held still), and the fact that the same
equation prices a call, a put, or an early-exercise contract with
only the edges changed. The slopes of that sheet are the Greeks.
Inputs: stock price, strike, volatility, rate, time. Outputs: delta
(the share count that hedges the option), gamma (how fast delta
changes), theta (the clock), vega (volatility), rho (the interest
rate). Run once on a three-month at-the-money call: about eight
dollars, delta fifty-four hundredths, gamma two hundredths, theta
about four cents a day, vega about twenty cents a point. The one
inside idea: every Greek is a local slope, so Greeks change as the
market moves, add across a book, and gamma and theta are locked with
opposite signs. The takeaway: ask which Greek dominates the risk of
a position right now. Ends with a prompt for your own AI model.
For educational purposes only; not financial, investment, tax, or
legal advice. Nothing here is a recommendation to buy or sell any
instrument. Past performance is not indicative of future results.
Nothing in this podcast is financial advice. All figures discussed are historical and for educational purposes only. Do your own research and consult a licensed professional before making investment decisions.
The trade that removes risk: Black-Scholes
Season 1 · Episode 8
Thursday, September 24, 2026 • Duration 17:25
Course episode eight, Wilmott chapter six. Price an option that
expires in months on a stock that moves continuously. Hold the
option and sell delta shares against it; over the next instant the
slope terms cancel exactly and what is left is deterministic, the
option's time decay plus the curvature term from Ito's lemma. A
riskless portfolio must earn the risk-free rate, and setting those
equal is the Black-Scholes equation, stated in words. What fell out:
the stock's expected return never appears, only its volatility, the
continuous version of the binomial tree's lesson. From equation to
price: the payoff at expiry anchors it, and for a plain call the
answer is the Black-Scholes formula, read off the bell curve. One
rule of thumb to carry: an at-the-money short-dated call is worth
about four tenths of the stock price times volatility times the
square root of time, so a three-month call on a hundred-dollar stock
at forty percent volatility is about eight dollars. What the price
means for a desk that hedges, and where the model bends. Vocabulary:
hedge portfolio, delta, riskless over an instant, the risk-free
rate, the Black-Scholes equation, boundary condition, the
Black-Scholes formula. Ends with a prompt to take to your own AI
model.
For educational purposes only; not financial, investment, tax, or
legal advice. Nothing here is a recommendation to buy or sell any
instrument. Past performance is not indicative of future results.
Nothing in this podcast is financial advice. All figures discussed are historical and for educational purposes only. Do your own research and consult a licensed professional before making investment decisions.
Mean reversion has a speed: Ornstein-Uhlenbeck
Season 1 · Episode 7
Friday, September 18, 2026 • Duration 17:24
Course episode seven, Wilmott chapter five, the first stochastic
equation you read rather than derive. A spread keeps drifting away
from some level and coming back. How fast, and is that a number?
Algebra first: tomorrow's deviation is a fraction of today's plus
noise; a fraction of nine tenths closes a gap of ten to nine, then
eight point one, then seven point three, and halves it in between
six and seven steps. A fraction of one is a random walk; above one
the gap explodes. You measure the fraction by regressing today's
deviation on yesterday's. Then the continuous version: theta is the
speed, mu is the home, sigma is the shove, and the half-life is the
natural log of two over theta, about seven days for a theta of a
tenth per day. The honesty: short half-life with small noise is
tradable, long half-life with large noise is not, and a half-life
measured on one window is a hypothesis until it holds on another.
Vocabulary: mean reversion, long-run mean, speed, half-life, spread,
stationarity, autocorrelation. Ends with a prompt to take to your own
model.
For educational purposes only; not financial, investment, tax, or
legal advice. Nothing here is a recommendation to buy or sell any
instrument. Past performance is not indicative of future results.
Nothing in this podcast is financial advice. All figures discussed are historical and for educational purposes only. Do your own research and consult a licensed professional before making investment decisions.
The calculus of randomness: Ito's lemma
Season 1 · Episode 6
Friday, September 18, 2026 • Duration 16:35
Course episode six, Wilmott chapter five, the first real calculus
episode. You hold something whose value depends on a price that
follows last episode's random walk. How does your value change when
the price jiggles? The ordinary answer, slope times the price change,
is wrong, and this episode shows why by hand: expand to second order;
on a smooth path the squared change vanishes, on a random path it is
proportional to the time step because a root-of-time change squared
is the time step itself, so it survives. That surviving curvature
term is Ito's lemma. Worked case: the logarithm of the price drifts
at mu minus half sigma squared, so a stock with ten percent drift and
forty percent volatility compounds at two percent. Why curvature is
worth money, why volatility appears squared from here on, and where a
desk that hedges a short option book lives. Vocabulary: slope,
curvature, Taylor expansion, the chain rule, Brownian motion, Ito's
lemma. Ends with a prompt to take to your own AI model.
For educational purposes only; not financial, investment, tax, or
legal advice. Nothing here is a recommendation to buy or sell any
instrument. Past performance is not indicative of future results.
Nothing in this podcast is financial advice. All figures discussed are historical and for educational purposes only. Do your own research and consult a licensed professional before making investment decisions.
Why prices can't be predicted, only described
Season 1 · Episode 5
Friday, September 18, 2026 • Duration 17:42
Course episode five, Wilmott chapter four. Last episode's tree had
two prices per step; real prices take many small steps. What can we
honestly say about where a price will be? This episode builds the
answer by hand: a coin-flip walk whose typical distance grows with
the square root of the number of steps, not the number of steps,
because the flips partly cancel. Then markets: a daily volatility
becomes an annual one by multiplying by about sixteen; drift grows
with time itself, so noise dominates short horizons and drift can
show over long ones. Why a point forecast is nearly worthless while
a distribution is useful, and why three up days tell you little.
Vocabulary: return, drift, volatility, random walk, independent
increments, the bell curve, standard deviation, lognormal. The first
calculus idea of the course: the square root of time, and why it
breaks ordinary calculus on random paths. The equation on the show's
cover, stated in words. Ends with a prompt to take to your own AI model.
For educational purposes only; not financial, investment, tax, or
legal advice. Nothing here is a recommendation to buy or sell any
instrument. Past performance is not indicative of future results.
Nothing in this podcast is financial advice. All figures discussed are historical and for educational purposes only. Do your own research and consult a licensed professional before making investment decisions.
Pricing without guessing: the binomial tree
Season 1 · Episode 4
Thursday, September 17, 2026 • Duration 16:03
Course episode four, Wilmott chapter three. Price a call that expires
in one step on a stock that can only go to one of two prices. The
temptation is to weight the outcomes by how likely you think they
are. Instead we build the hedge by hand with round numbers: own half
a share against the call so the portfolio is worth the same in both
states, and the price falls out with no probability of up or down
used at all. Then the risk-neutral probability: the same price from
pretending the stock earns the risk-free rate, and why that is
bookkeeping that falls out of the hedge, not a belief. What a small
positive rate changes. From one step to a tree, and why the limit is
where the calculus begins next. Vocabulary: up and down state, the
hedge, delta, riskless portfolio, risk-neutral probability,
discounting. The last calculus-free episode. Ends with a prompt to
take to your own AI model.
For educational purposes only; not financial, investment, tax, or
legal advice. Nothing here is a recommendation to buy or sell any
instrument. Past performance is not indicative of future results.
Nothing in this podcast is financial advice. All figures discussed are historical and for educational purposes only. Do your own research and consult a licensed professional before making investment decisions.
A bet you can take apart
Season 1 · Episode 3
Thursday, September 17, 2026 • Duration 16:53
Course episode three, Wilmott chapter two. You open a position that
looks complicated, an iron condor, and ask: what did I actually buy?
This episode teaches the vocabulary (option, call, put, strike,
expiry, premium, payoff versus profit, intrinsic value, in and out
of the money, long and short, spread), then the dynamic: draw a call
as a hockey stick, a short put as its mirror, stack them, and see
the condor as two credit spreads whose payoff is just the sum of the
pieces. The driving-time algebra is one line: the larger of zero and
a difference. Then the first pricing law of the show, put-call
parity, proved with the same arbitrage habit as last episode and
checked in round numbers, and what it buys you: any one of call,
put, stock, or cash can be built from the other three, so a
mispriced piece is visible. No calculus yet. Ends with a prompt to
take to your own AI model.
For educational purposes only; not financial, investment, tax, or
legal advice. Nothing here is a recommendation to buy or sell any
instrument. Past performance is not indicative of future results.
Nothing in this podcast is financial advice. All figures discussed are historical and for educational purposes only. Do your own research and consult a licensed professional before making investment decisions.
What a market price actually is
Season 1 · Episode 2
Thursday, September 17, 2026 • Duration 17:37
Course episode two, Wilmott chapter one. You want to own something
later at a price fixed today. What should that price be? Not what
you think it will be worth. This episode builds the answer from
scratch: the vocabulary (spot, forward, future, long, short,
delivery, the risk-free rate, arbitrage), then the dynamic. The
forward price is the spot price carried forward at the risk-free
rate, because any other price hands someone a riskless profit. We
walk that arbitrage in both directions in plain words, do the
driving-time algebra with round numbers, and then say honestly what
the clean rule leaves out: storage cost, income, and convenience
yield. No calculus yet, on purpose. Ends with one prompt to take to
your own AI model.
For educational purposes only; not financial, investment, tax, or
legal advice. Nothing here is a recommendation to buy or sell any
instrument. Past performance is not indicative of future results.
Nothing in this podcast is financial advice. All figures discussed are historical and for educational purposes only. Do your own research and consult a licensed professional before making investment decisions.
A new way to learn math
Season 1 · Episode 1
Thursday, September 17, 2026 • Duration 05:28
A five-minute declaration. How math is learned is changing: from
rigor-first, bottom-up teaching to top-down learning that starts from
a real problem, with an AI model as a patient expert. The cap on how much
math you can learn is the quality of your relationship with the model
you prompt.
This podcast is the first step in that new way. It teaches two things
for the dead time in your day: the dynamics of quantitative finance,
what moves, why, and what the calculus underneath is saying, without
the rigor; and the vocabulary a quant uses, so your time with an AI model
is spent asking sharp questions. Episodes follow the order of a quant
finance textbook, one dynamic per episode, with real trading
problems as the worked examples. Derivations and rigor live
in the show notes.
For educational purposes only; not financial, investment, tax, or
legal advice. Nothing here is a recommendation to buy or sell any
instrument. Past performance is not indicative of future results.
Nothing in this podcast is financial advice. All figures discussed are historical and for educational purposes only. Do your own research and consult a licensed professional before making investment decisions.